Dow futures indicated an upward trajectory on Monday, implying a possible rebound on Wall Street following significant declines in technology stocks throughout October, driven by escalating apprehensions regarding the magnitude of expenditures on artificial intelligence. Investors are currently focusing on a new set of corporate earnings, highlighted by Apple’s initial results under the leadership of CEO John Ternus. Concurrently, attention is also directed toward the ongoing Iran conflict, a significant hack involving a major cryptocurrency exchange, and the upcoming U.S. midterm elections.
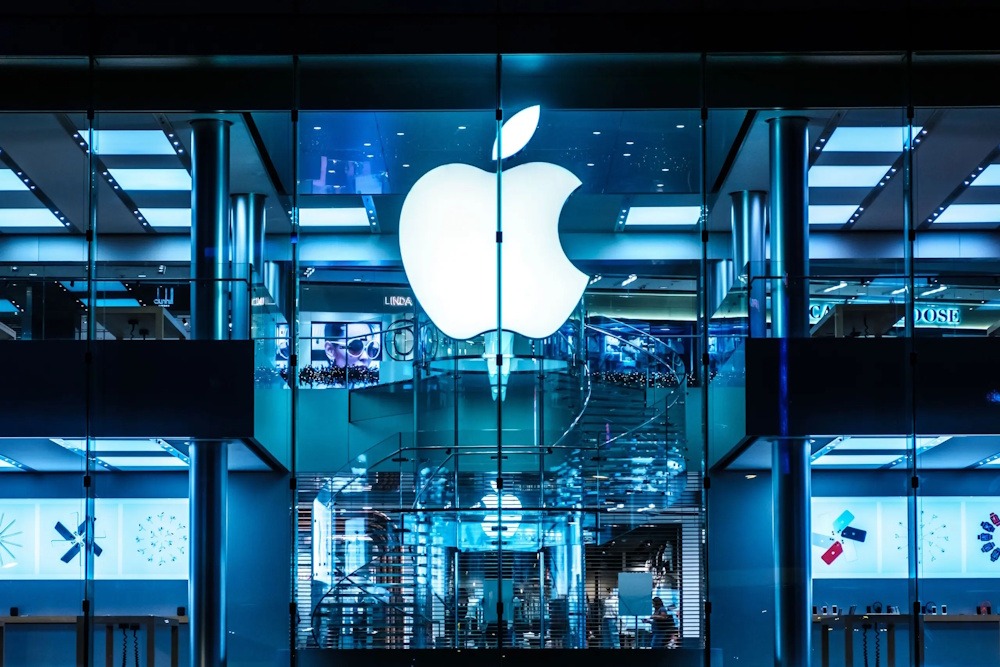
Apple is set to announce its earnings on Monday, with investors keenly awaiting insights from new CEO John Ternus regarding the potential of the company’s recent product launches to drive growth, particularly in light of increasing memory-chip costs that pose a risk to profit margins. Ternus, who succeeded Tim Cook in September, is conducting his inaugural earnings call as CEO following the introduction of multiple new products, which encompass Apple’s first foldable iPhone, a smart home hub, and its initial touchscreen laptops. The devices commenced shipping in the company’s ongoing fiscal first quarter. Investors will focus on three critical aspects: Apple’s forecast for the vital holiday quarter, Ternus’ insights regarding artificial intelligence and the updated Siri, and the influence of increased memory-chip prices on profitability. Analysts anticipate that increasing component costs will exert pressure on profit growth, likely resulting in the slowest pace observed in six quarters. Apple has once again secured its status as the world’s most valuable publicly traded company as of Friday, surpassing Nvidia. Despite a 1.2% decline in its shares, Apple concluded the session with a market capitalisation of $5.03 trillion. Nvidia’s valuation decreased to $4.93 trillion following a 4.2% decline in its stock, as investor apprehensions regarding aggressive AI expenditures resurfaced. Apple’s results may serve as a critical evaluation of the company’s ability to maintain growth amidst increasing input costs, particularly in light of its recent product launches and AI strategy. Its performance may also offer insights into investor appetite for large technology companies, especially as markets reevaluate the returns anticipated from substantial AI investment.
Binance customers withdrew $3.64 billion, or approximately 2.1% of the exchange’s assets, as the world’s largest cryptocurrency exchange resumed services following a security breach associated with North Korea. The incident reportedly resulted in $6.3 billion being stolen from the platform last week. Binance indicated that withdrawals were stabilising following an initial surge, while deposit volumes continued to be substantial, aiming to reassure customers regarding the platform’s financial standing. The exchange reported total assets under management of $171 billion as of October 28 and has approximately 335 million registered users worldwide. The magnitude of the reported theft has heightened apprehensions regarding the security of cryptocurrency platforms and the likelihood of additional disturbances throughout the sector. Bitcoin experienced a modest rebound over the weekend, following a decline that saw it reach a six-week low on Friday, with trading levels surpassing $78,000 on Monday. Ether experienced a modest rebound, rising to approximately $2,287 after previously declining to a two-month low. The withdrawals underscore the rapidity with which confidence can be challenged in the cryptocurrency market after a significant security breach. While Binance has indicated that flows are stabilising, ongoing withdrawals or additional uncertainty may impact the overall sentiment in the digital asset market.
U.S. stock index futures experienced an uptick early Monday, indicating a potential rebound following October’s technology-driven decline, as investors anticipated a week filled with corporate earnings reports. By 03:50, S&P 500 futures had risen 0.46% to 7,614 points, Nasdaq 100 futures had gained 0.75% to 28,753 points, and Dow Jones futures were up 0.28% at 52,075 points. Technology shares experienced a rebound across Asian markets, contributing to the overall recovery in futures. Investors are poised to scrutinise earnings reports from significant corporations, with Apple presenting its results on Monday and Advanced Micro Devices following suit on Tuesday. Palantir Technologies and Berkshire Hathaway are set to announce their results on Monday.
Oil prices experienced a decline exceeding 3% on Monday, as optimism surrounding diplomatic initiatives aimed at resolving the U.S.-Israeli conflict with Iran alleviated pressing worries regarding potential supply disruptions. Brent crude futures for January delivery experienced a decline of 3.3%, settling at $109.70 per barrel by 00:27. Meanwhile, U.S. West Texas Intermediate crude futures saw a decrease of 3.5%, reaching $100.48 per barrel. The decline followed strong gains in recent sessions, with the absence of a major escalation over the weekend encouraging some investors to take profits. Both benchmarks concluded October with an increase of nearly 15%. U.S. President Donald Trump reportedly communicated to Israeli Prime Minister Benjamin Netanyahu during a phone call on Saturday that he favoured allowing diplomacy additional time before determining whether to reinstate military action, sources indicated. Netanyahu is said to have advocated for the resumption of U.S. strikes soon after the midterm elections. Declining oil prices may alleviate certain inflationary pressures and mitigate apprehensions regarding elevated energy expenses for both enterprises and consumers. However, crude remains elevated after October’s rally, leaving markets sensitive to any setback in diplomatic efforts or renewed disruption to supplies.
The U.S. midterm elections, scheduled for Tuesday, are another major focus for investors, with the results expected to influence the legislative direction of President Donald Trump’s second term. All 435 seats in the House of Representatives and 35 Senate seats are up for election. Trump and Republicans are approaching the vote amid a difficult environment, characterised by voter dissatisfaction stemming from elevated petrol prices and the ongoing conflict with Iran, which is influencing the political landscape. A recent poll put Trump’s approval rating at 31%, its lowest level in the survey. A Democratic majority in both chambers of Congress may complicate the administration’s efforts to push forward its policy agenda. A divided Congress, in this context, may compel the White House to increasingly depend on executive actions. The election outcome may influence the trajectory of fiscal policy, regulatory frameworks, trade dynamics, and other critical domains pertinent to businesses and financial markets. A shift in congressional control may further complicate the administration’s policy initiatives, likely contributing to increased uncertainty for investors throughout the remainder of Trump’s term.